Las Vegas mortgage broker · Licensed in 9 states Home loans for every kind of buyer.

First home or fifth, VA or self-employed, buying or refinancing: our team handles every major loan type, compares pricing across multiple wholesale lenders and updates you at every milestone. From the first call to the keys, nobody gets left in the dark.

Rather talk now? Call or text (702) 766-7762

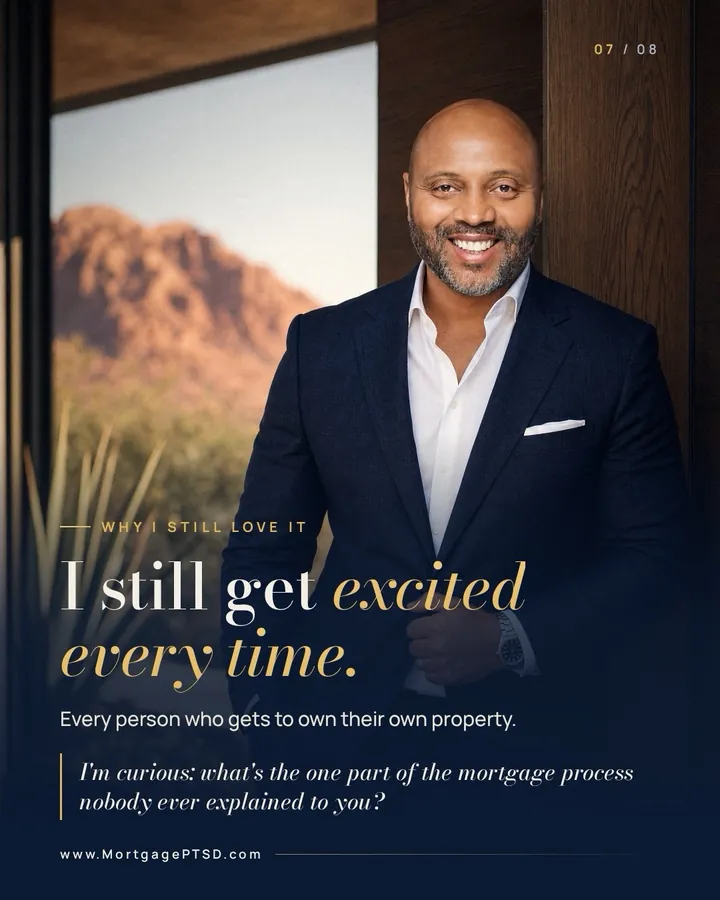
Fabion Medhanie, smiling in a navy suit, at the open glass door of a modern desert home with agave, yucca, bougainvillea and red rock mountains beyond
MortgagePTSD teamnow

Good news: the appraisal is in. Next up is final underwriting, and we’ll text you and your agent the minute it clears.

Example milestone update
Every kind of buyer · Every major loan type

Everybody who wants a place of their own.

MortgagePTSD is a Las Vegas mortgage broker team for first-time buyers, move-up buyers, veterans, self-employed borrowers, investors and homeowners, in Nevada and 8 more states. Pick your situation to see how we’d approach it.

Single-story white stucco home with a navy front door, pink bougainvillea and desert landscaping below the mountains

Your first home, explained in plain English.

Many first-time buyers assume they need 20% down and perfect credit. Often you don't. Conventional loans have low down payment options for first-time buyers, FHA is built for credit that isn't perfect, and gift money from family is allowed on many programs. We set a budget you're comfortable with, check you for Nevada down payment assistance, and walk you through every step.

  • Low down payment conventional options
  • FHA loans insured by HUD
  • Gift funds allowed on many programs
  • Nevada down payment assistance check
LowDown payment options
FHAHUD-insured option
6Steps, mapped below

Sources: Fannie Mae, 97% LTV options · HUD, FHA credit scores · HUD, how FHA helps buyers

Your mortgage team

It takes a team to get you home.

One point of contact, and a whole crew of specialists behind it. Here’s who works your file, and when you’ll hear from us.

  • Fabion Medhanie, your loan officer

    Your direct line from the first call to the keys. Structures the loan, shops it across multiple wholesale lenders and owns the plan.

  • Loan officer assistant

    Collects documents, keeps your checklist moving and follows up, so nothing sits waiting on anyone.

  • Processing and underwriting

    Barrett Financial's processing team orders the appraisal, title and verifications, then packages your file for the lender's underwriter.

  • Realtor partner network

    Need an agent? We'll connect you with a trusted local Realtor. Already have one? They get real updates from us at every milestone.

  • Transaction coordinators

    Keep contract dates, inspection deadlines and paperwork on schedule between the agents, title and our team.

  • Title and escrow

    Prepare the closing documents, handle the funds and record your deed. We confirm wiring instructions by phone, every time.

The route from first call to keys

Six steps. Every one has an owner.

Every purchase in Las Vegas follows the same six steps. Here’s what happens at each one, who on the team is handling it, the mistake to avoid, and the update you’ll get when it’s done.

Step 1 of 6 · Week 0 · about 30 minutes

Numbers and budget

Who’s on it: Fabion and you

Before you shop, set a budget that includes everything, not just the mortgage payment: property tax, homeowners insurance, PMI and HOA. The full payment plus reserves.

Pitfall: Falling in love with a price a lender will approve but your life can't absorb. Approval isn't the same as comfortable.

You get the budget breakdown in writing.

  • Pull your credit reports (no score impact)
  • Calculate gross monthly income
  • List monthly debts: cars, cards, student loans
  • Run a real estimate with the calculator below
Between approval and closing

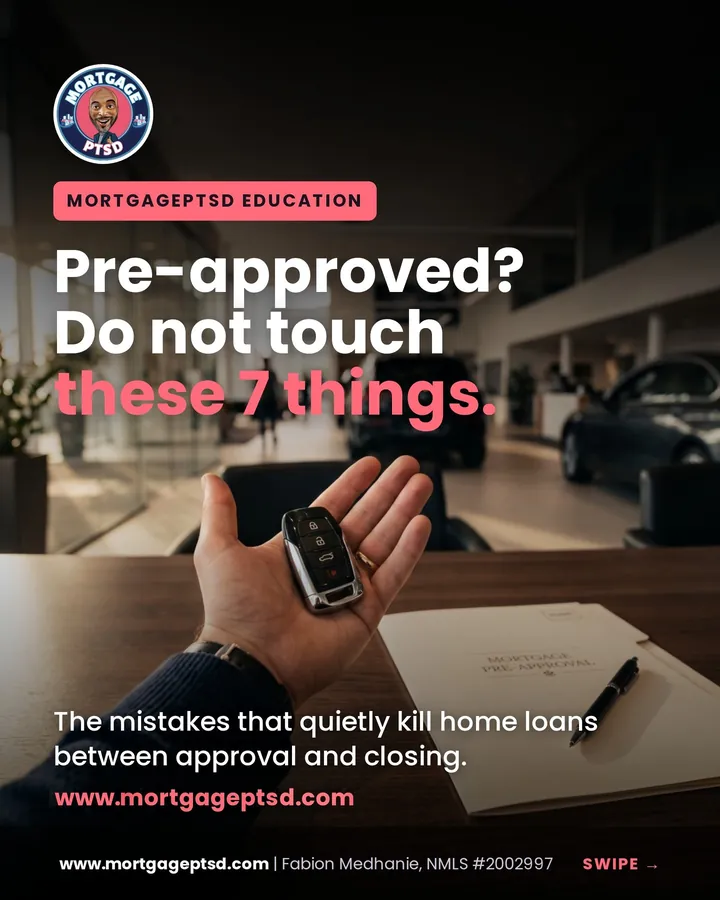
Pre-approved? Don’t touch these 7 things.

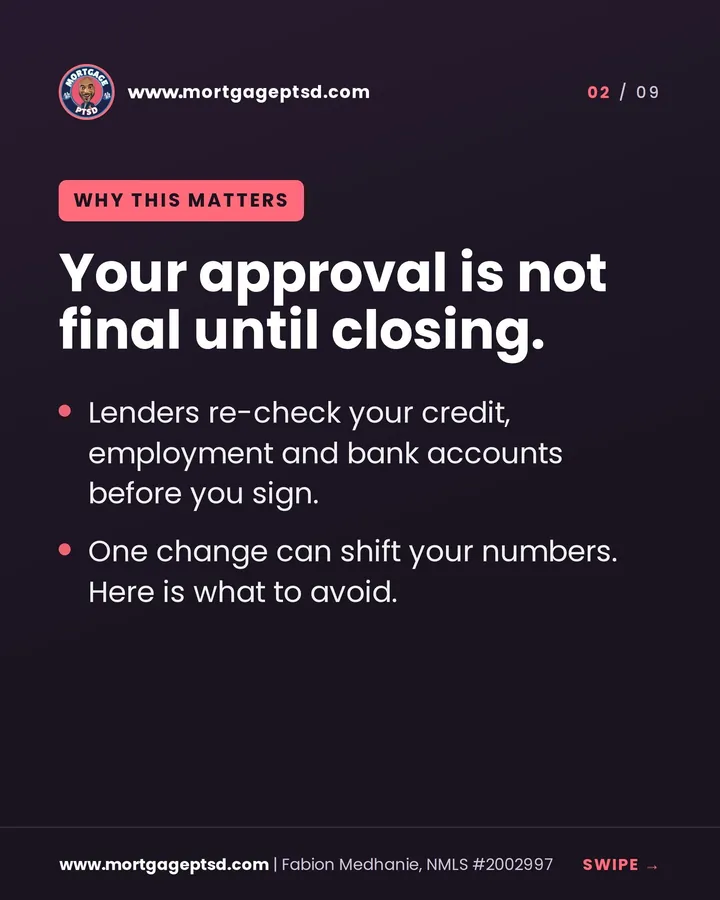
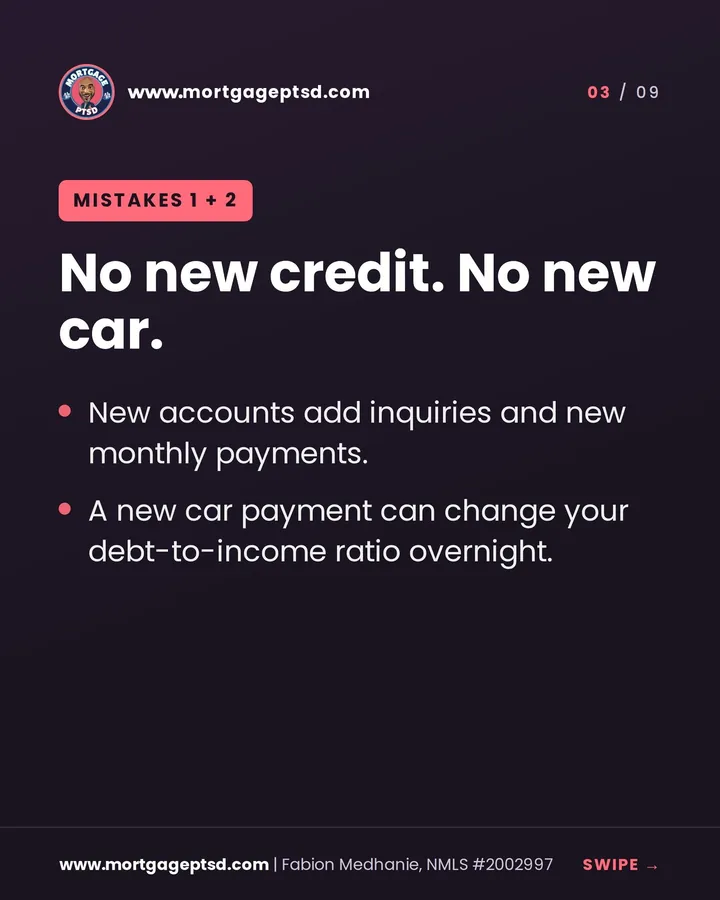
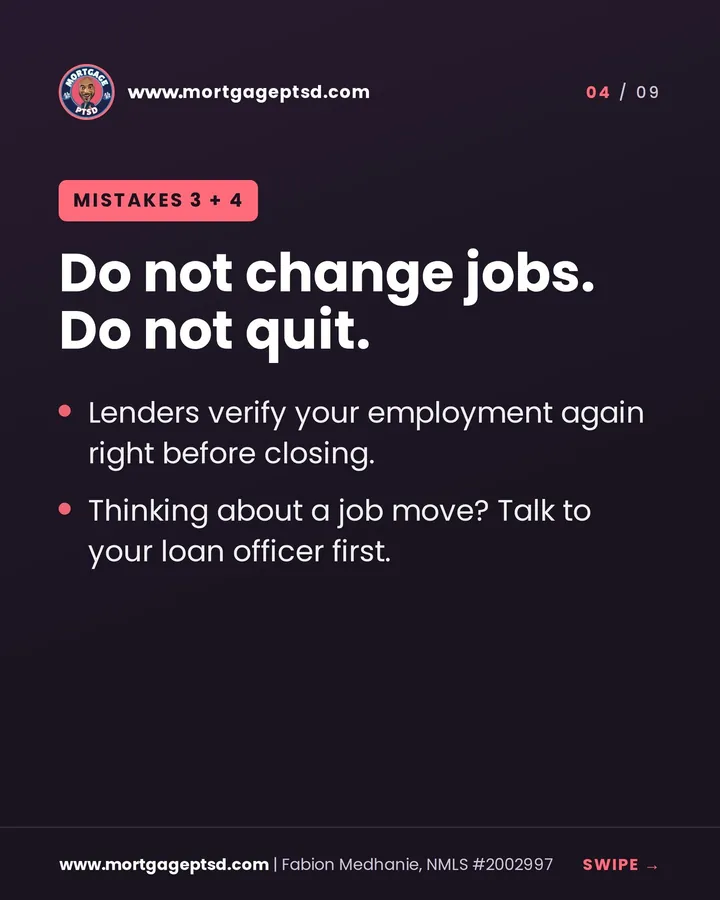
Your approval isn’t final until closing. Lenders re-check credit, employment and bank accounts before you sign, so one change can shift your numbers. Swipe through, and when in doubt, text us first.

Text the team a question 
Read the 7 things as text
  1. Pre-approved? Do not touch these 7 things: the mistakes that quietly kill home loans between approval and closing
  2. Why this matters: your approval is not final until closing; lenders re-check credit, employment and bank accounts
  3. Mistakes 1 and 2: no new credit, no new car
  4. Mistakes 3 and 4: do not change jobs, do not quit; talk to your loan officer before any job move
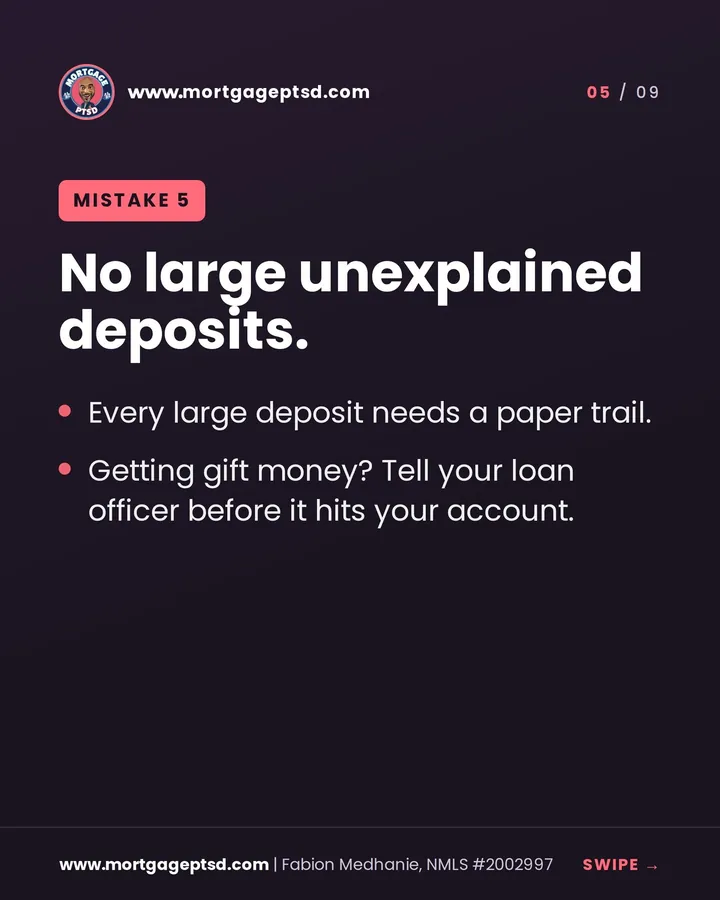
  5. Mistake 5: no large unexplained deposits; every large deposit needs a paper trail
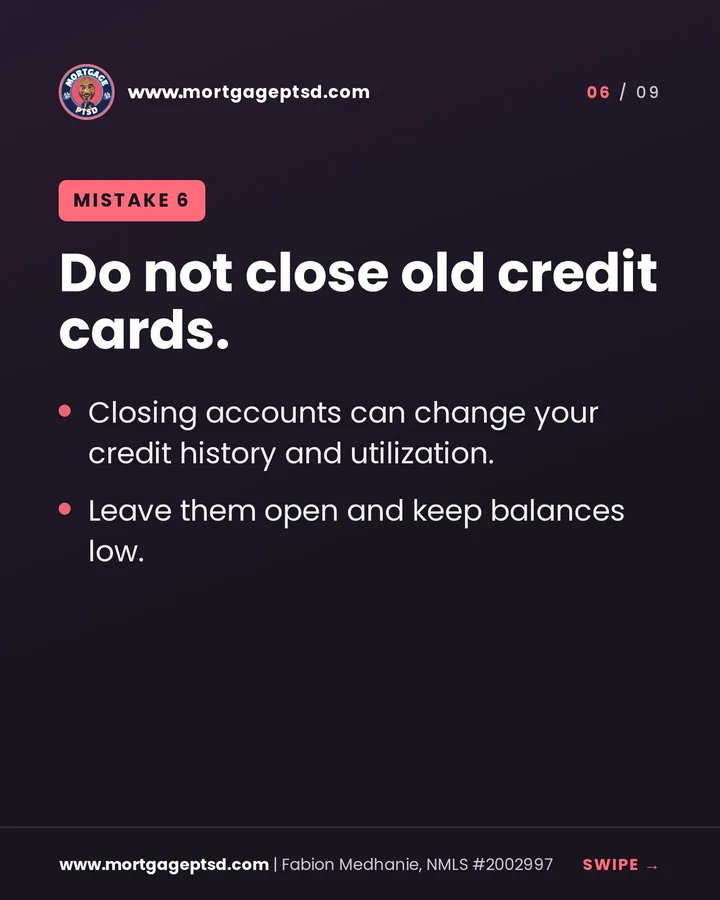
  6. Mistake 6: do not close old credit cards; leave them open and keep balances low
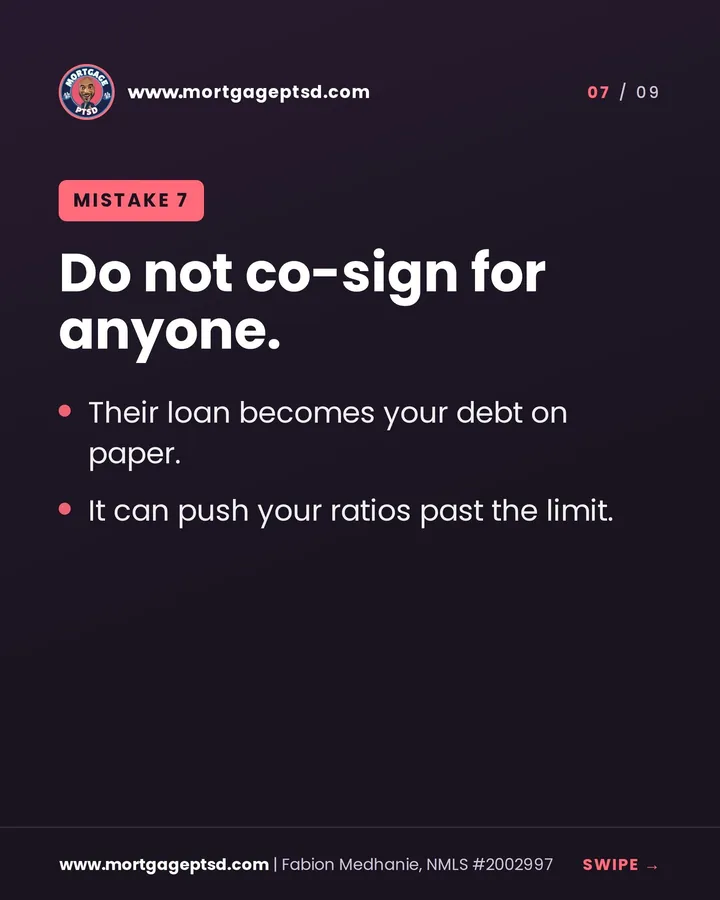
  7. Mistake 7: do not co-sign for anyone; their loan becomes your debt on paper
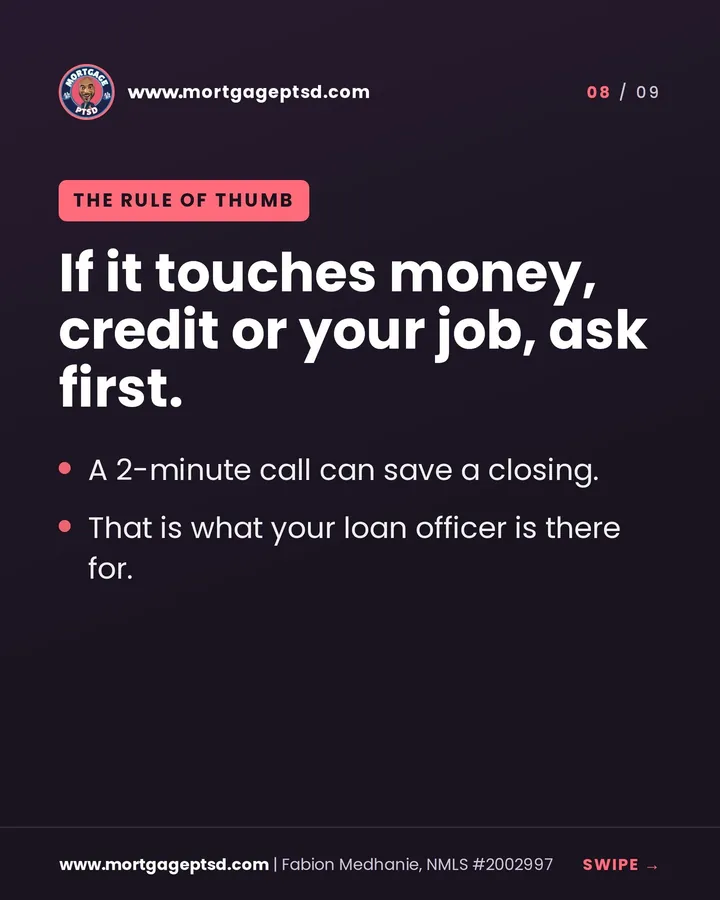
  8. The rule of thumb: if it touches money, credit or your job, ask first
  9. Ready to start the right way? Start your application online or book a free 15-minute call
Why the name

MortgagePTSD is real.

The unreturned calls. The one number you were told to take or leave. The fee that showed up in week five. If a past mortgage left a mark, you’re not imagining it.

So I named the company after the problem, and built a team around the fix.

A stressed homebuyer at a kitchen table covered in paperwork
Last time
A relaxed homeowner on the phone with a coffee, calm and informed
This time
Drag the line. Which side sounds like your last mortgage?Book a 15-minute call 

“They went quiet on me.”

Here: you hear where your file stands before it occurs to you to ask, and you have a direct line, not a queue.

“I only ever got one number.”

Here: a bank can only show you what that bank sells. As a broker we put a network of lenders in competition and lay the options side by side. Then you pick, not us.

“The number changed at the end.”

Here: you get an itemized Loan Estimate within three business days of applying, and if a number moves, you hear it from us before you see it on your Closing Disclosure.

“They wanted me to fax it.”

Here: apply, e-sign and upload everything from your phone. Nobody here will send you looking for a fax machine.
Mortgage payment calculator

What would your mortgage really cost each month?

Not the teaser payment, the real one: price, down payment, rate, term, taxes, insurance and HOA, updating live with a year-by-year schedule. No sign-up. When you want it, I’ll turn your exact scenario into a Homebuying Snapshot you can keep.

Start with your own numbers. Nothing is filled in for you, and nothing you type is saved unless you ask for the Snapshot.

$
$100k$2M
%
0%50%

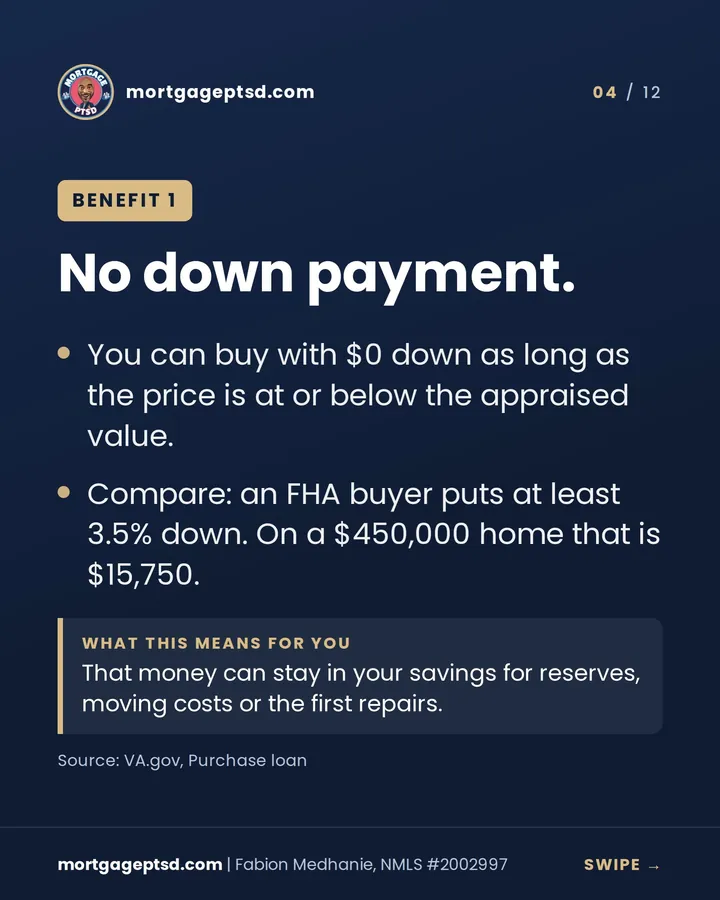
Eligible veterans can buy with no down payment when the price is at or below the appraised value (VA.gov).

%
yrs
$
$
$

Use any rate you want to test. This site does not quote rates; ask for today’s pricing on your exact scenario. Property tax and insurance fill in as rough estimates from the price until you type your own.

Estimated monthly payment
Your numbers
  • Principal and interest-
  • Property tax-
  • Home insurance-
Loan amount-
Total interest-
Total of payments-
Payoff date-

Affordability read

To keep this inside the classic 28% guideline, plan on household income around -/yr.

Ways to lower this payment

  • ✓

    Enter a price, rate and term and this fills in with three ways to lower your payment.

Want to keep this? I’ll turn your exact scenario into a one-page Homebuying Snapshot: your numbers, three ways to lower the payment, your schedule and your next step.

Or start a real pre-approval

General estimates based on the figures you enter, not a rate offer or approval. Actual rates and payments depend on your full application.

What clients say about MortgagePTSD on Google

Communication was clear, friendly, and prompt, which made the entire process effortless and enjoyable.

Mike Pullin · Google review · Aug 2025

5.0★★★★★

Across 13 Google reviews, as of October 2026. Excerpts quoted word for word.

Worked with us? Leave a Google review. Honest feedback helps the next buyer.

★★★★★What truly sets Fabion apart is his professionalism and communication. He follows through, keeps you updated, and genuinely cares about the people he works with.
Jennifer Moroch · Google review · Jan 2026
★★★★★They made it easy and understandable. They didn't give up or think about giving up. They stayed with us throughout the whole process.
Gene Wolfe · First-time buyer · Google review · Aug 2025
★★★★★I have seen Fabion first hand meet with clients at a coffee shop to clearly communicate the process and figure out how to make someone’s dream of homeownership possible.
Michael Burr · Realtor and referral partner · Google review · Sep 2025
★★★★★He guided us through a complex and at times overwhelming financing process with outstanding professionalism, endless patience, and genuine heart.
Melanie Guersoy · Bought in Florida · Google review · Aug 2025
★★★★★He was always available for questions and patiently explained the entire process to us.
Ilka Schumacher · Moved to Las Vegas · Google review · Aug 2025
Your turnWant a story like these? It starts with one conversation.Book a call →
Sprechen Sie Deutsch? Ich auch.
The broker who leads the team

Hi, I’m Fabion. Let’s get you home.

Born in Germany, home in Las Vegas. Retired U.S. Army veteran and the licensed mortgage loan originator behind MortgagePTSD, licensed in 9 states.

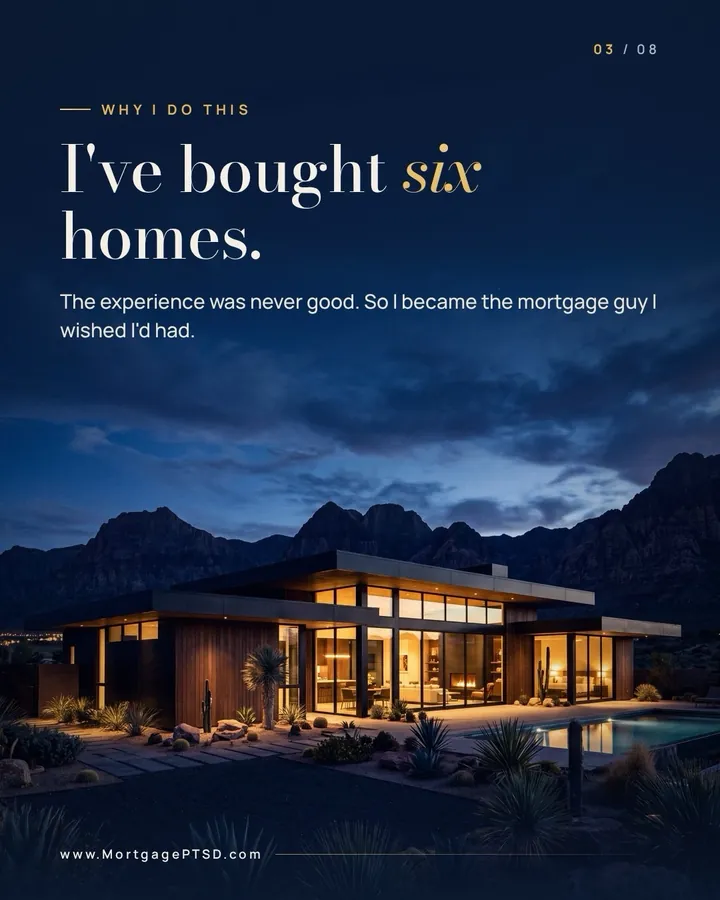
“I’ve bought six homes. The experience was never good. So I became the mortgage guy I wished I’d had.”

Today I lead a team that serves first-time and move-up buyers, veterans, business owners, investors and homeowners. Every file gets the same process: pricing compared across multiple wholesale lenders, the numbers in plain language, and an update at every step. Strong credit and a solid down payment? We keep that path simple. If a file has a wrinkle, you hear about it early, along with the route around it.

Service
U.S. Army, retired
Licensed loan originator
NMLS #2002997
Powered by
Barrett Financial Group, NMLS #181106
Languages
English and Deutsch
Based in
North Las Vegas, Nevada
Licensed in
NVCACOFLGANCTNTXVA

More about Fabion 

Read Fabion’s intro as text
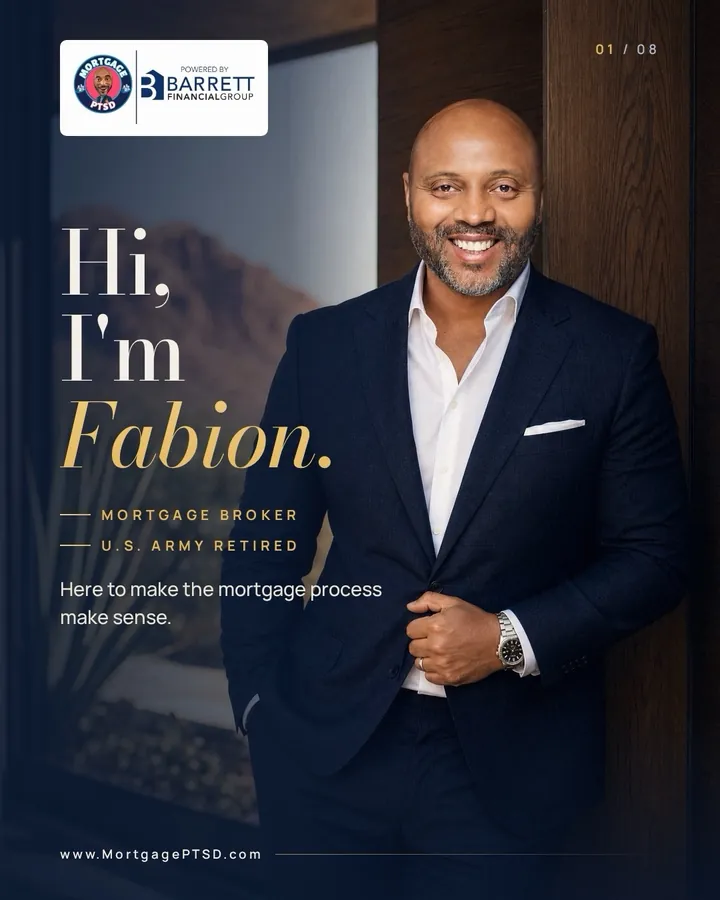
  1. Hi, I'm Fabion: mortgage broker, U.S. Army retired, here to make the mortgage process make sense
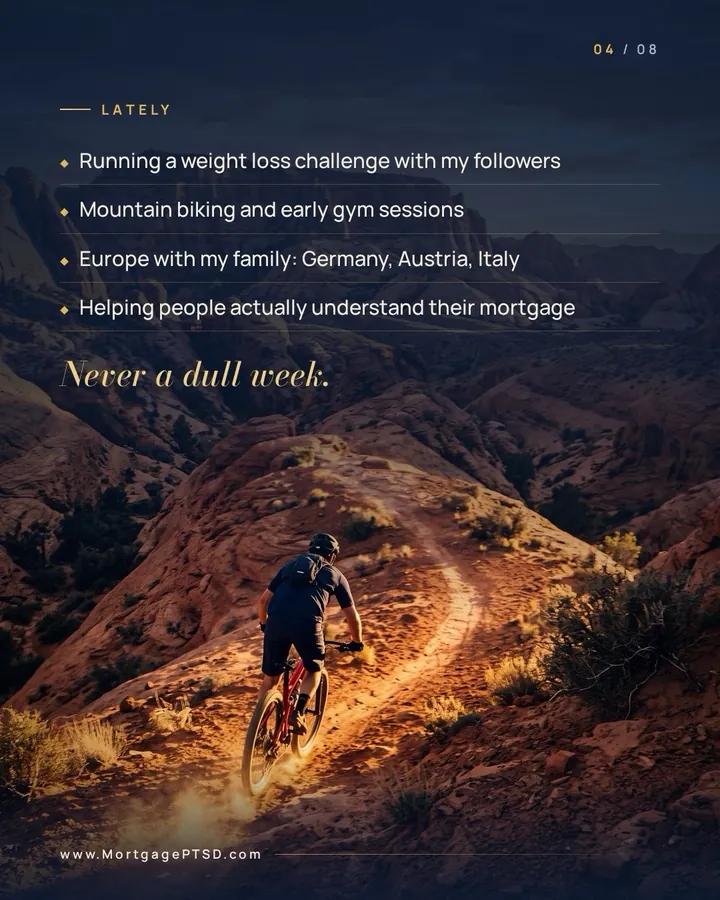
  2. Born in Germany, home in Las Vegas: dad, gym regular, mountain biker, FC Bayern always
  3. I've bought six homes. The experience was never good, so I became the mortgage guy I wished I'd had
  4. Lately: a weight loss challenge with followers, mountain biking, Europe with family, and helping people understand their mortgage
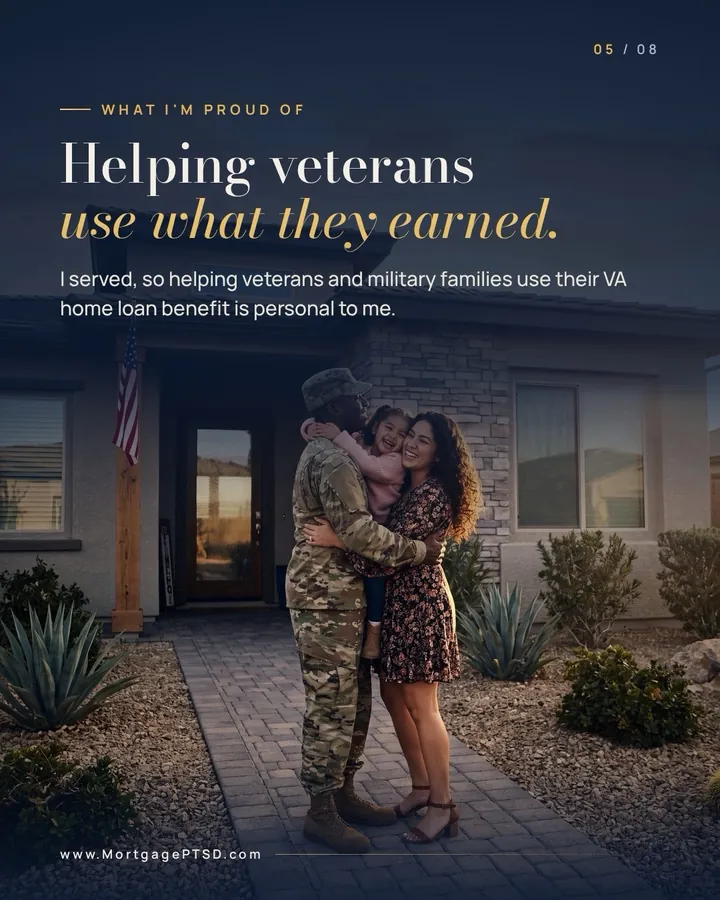
  5. What I'm proud of: helping veterans and military families use the VA home loan benefit they earned
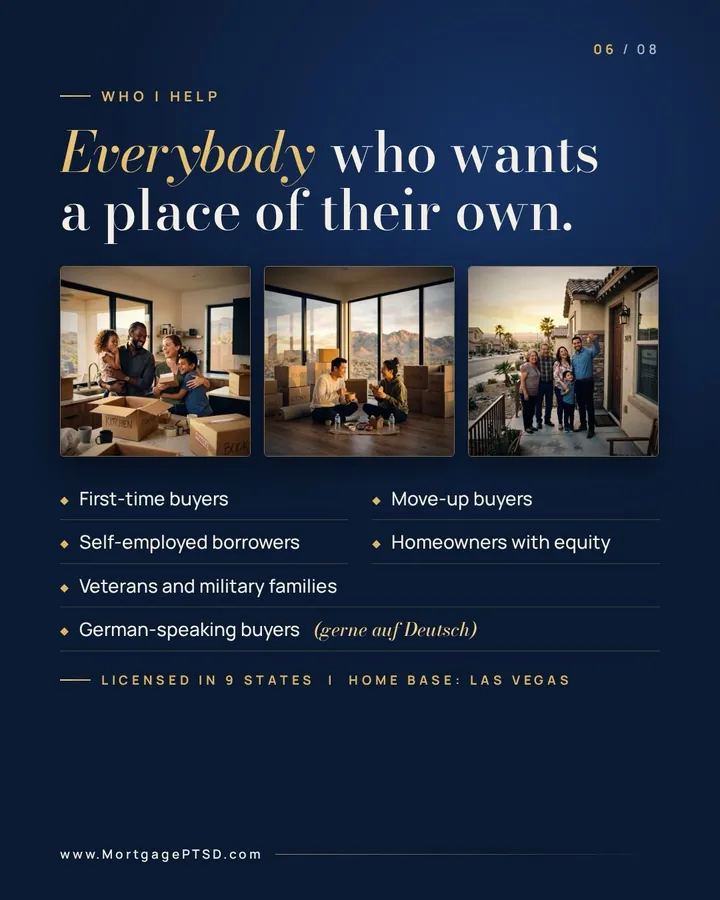
  6. Everybody who wants a place of their own: first-time buyers, move-up buyers, self-employed borrowers, homeowners with equity, veterans and German-speaking buyers
  7. Why I still love it: I still get excited every time a person gets to own their own property
  8. Fabion Medhanie, NMLS #2002997, MortgagePTSD powered by Barrett Financial Group: call or text 702-766-7762
Straight answers, no call required

Rather just understand it first?

Short, no-fluff answers to the questions that come up most, from first-time buyers to homeowners. No email gate.

Got a question these didn’t cover? Ask us that one 

Questions people ask first

Las Vegas mortgage questions, answered before you call.

Who we help, how brokers get paid, how long closing takes, how credit and down payments really work, and who’s on your team. Still curious? Ask us directly.

Ask us your question 

Getting started

Who does MortgagePTSD help?

Everybody who wants a place of their own: first-time buyers, move-up buyers, veterans and military families, self-employed and 1099 borrowers, real estate investors, homeowners refinancing or tapping equity, and German-speaking buyers.

The team handles conventional, FHA, VA, USDA, jumbo, bank statement, 1099, DSCR, refinance, cash-out, first-position HELOC and foreign national loans in Nevada, California, Colorado, Florida, Georgia, North Carolina, Tennessee, Texas and Virginia.

Do you only do VA loans?

No. Fabion is a retired U.S. Army veteran and VA loans are a big part of the work, and so are conventional, FHA, jumbo, self-employed, investor and refinance loans.

Whatever the loan, the process is the same: pricing compared across multiple wholesale lenders, the numbers in plain language, and an update at every milestone.

I have great credit and 20% down. Do I still need a mortgage broker?

That's usually the most straightforward file there is, and it's exactly where comparing lenders pays off. We price your scenario across multiple wholesale lenders and show you the options side by side, so you pick the best fit instead of taking the first offer.

With 20% down on a conventional loan there's no PMI, and we keep the path simple: clear checklist, e-sign from your phone, updates at every step.

Source: CFPB, removing PMI, last verified October 23, 2026.

I'm just looking. I'm not ready to apply yet.

That's the best time to talk. People who check where they stand months ahead usually end up in better shape than the ones who call after an offer is accepted.

You're not applying for anything and you're not committing to us. If we can't help, we'll say so and point you somewhere that can.

How long does it take to close on a home loan?

Your purchase contract sets the closing date, and the loan is planned backward from it. Federal rules require your Loan Estimate within three business days of applying and your Closing Disclosure at least three business days before you close.

In between, the appraisal, title and underwriting conditions set the pace, so sending documents early is the part you control.

Source: CFPB, Regulation Z 1026.19 (Loan Estimate and Closing Disclosure timing), last verified October 23, 2026.

Will getting a mortgage quote hurt my credit score?

No. The calculator and the Homebuying Snapshot on this site pull nothing: no soft inquiry, no hard inquiry, no Social Security number.

When you do move to a real pre-approval, FICO groups mortgage inquiries made close together into one: any 14-day span on older score versions and any 45-day span on newer ones. Shop inside two weeks and you're covered either way.

Source: myFICO, rate shopping, last verified October 23, 2026.

Should I compare a few lenders before choosing one?

Yes, and be wary of anyone who tells you not to. Send us the other quotes and we'll read them line by line and tell you plainly which one wins, even when it isn't ours.

Rate alone is where most people get caught: the lowest rate on the sheet often has points baked in, or lender credits that vanish at closing.

My bank already gave me a number. Why use a mortgage broker?

A bank can only offer its own menu. A broker puts a network of lenders in competition for your file, so you're comparing instead of assuming.

Sometimes the bank still wins, and when it does we'll tell you to take it. What did they quote you?

Loan questions

Can I get a mortgage if I'm self-employed?

Yes. With two years of tax returns, a conventional or FHA loan often works. If write-offs shrink your taxable income, bank statement programs (12 or 24 months of statements), P&L-only and 1099-only programs can qualify you on deposits or gross receipts instead.

We'll look at both routes and tell you which one prices better before you apply.

What is a DSCR loan?

A DSCR (debt service coverage ratio) loan qualifies an investment property on its rental income compared with its monthly payment of principal, interest, taxes, insurance and HOA, instead of on your personal income.

The higher the ratio, the more of the payment the rent covers. You can usually close in your own name or an LLC. See the Nevada DSCR guide.

Is my credit good enough to get a mortgage?

Possibly better than you think. For FHA, a 580 score is eligible for maximum financing (3.5% down), and 500 to 579 is limited to 90% loan-to-value, meaning 10% down. The VA doesn't publish a minimum score; lenders set their own.

The most expensive thing we see is people ruling themselves out before anyone has looked at their file.

Source: HUD, FHA credit scores, last verified October 23, 2026.

Do I need a 20% down payment to buy a home?

No. FHA allows 3.5% down with a 580+ score, VA can be $0 down, and conventional loans can go as low as 3% down for first-time buyers. Twenty percent isn't a requirement; it's the point where PMI isn't needed on a conventional loan.

Worth sitting with: if you've been saving toward 20% for years, what has the rent you paid over that stretch actually bought you?

Source: Fannie Mae, 97% LTV options, last verified October 23, 2026.

What is PMI, and when does it come off?

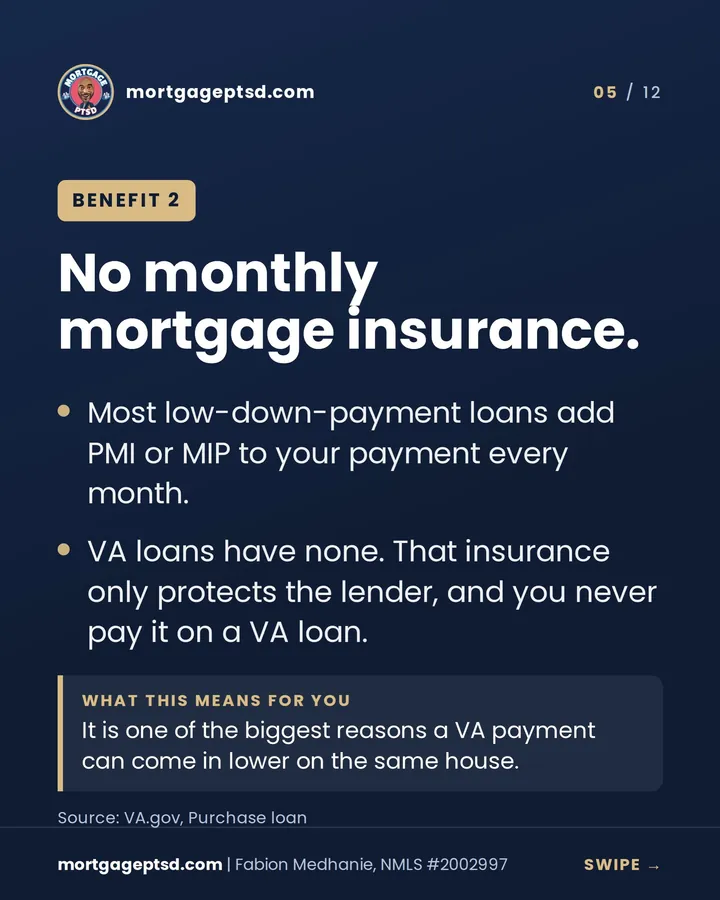
PMI is insurance you pay on a conventional loan when you put down less than 20%. It protects the lender, not you. You can ask to cancel it once your balance reaches 80% of the home's original value, and it ends automatically when your balance is scheduled to reach 78%, as long as you're current.

One catch: those thresholds use the original value, not today's. If your home has appreciated, that's a conversation to have with us.

Source: CFPB, removing PMI, last verified October 23, 2026.

About the team

What is MortgagePTSD?

MortgagePTSD (Pretty Terrific Service Department) is the mortgage team led by Fabion Medhanie, a retired U.S. Army veteran and licensed mortgage loan originator (NMLS #2002997) based in North Las Vegas, powered by Barrett Financial Group (NMLS #181106).

The name is the point: bad mortgage experiences leave a mark, and this team is built to be the opposite. Clear numbers, a direct line, and an update at every milestone.

Who will be working on my loan?

A team, with one point of contact. Fabion structures and prices your loan, a loan officer assistant keeps documents and follow-ups moving, Barrett Financial's processing team prepares the file for the lender's underwriter, transaction coordinators keep contract dates on track, and title and escrow handle closing.

Need a Realtor? We'll connect you with one from our partner network. Already have one? They'll get updates from us at every milestone.

What does a mortgage broker do, and how is that different from a bank?

A bank lends its own money and can offer only its own loan programs. A mortgage broker is licensed to arrange your loan with outside wholesale lenders, so one application can be priced against several lenders' programs and you choose from the options side by side.

Underwriting and final approval still come from the lender that funds the loan, which is why no broker can promise approval.

How do mortgage brokers get paid?

A mortgage broker is paid either by the lender or by you, never both on the same loan. Federal rules ban pay tied to your loan's interest rate or terms. If you pay the broker directly, it shows on your Loan Estimate. Either way, it shows on your Closing Disclosure, so you can see what was paid and by whom.

Source: CFPB, Regulation Z 1026.36 (loan originator pay), last verified October 23, 2026.

Which states is Fabion Medhanie licensed in?

Nine: Nevada, California, Colorado, Florida, Georgia, North Carolina, Tennessee, Texas and Virginia. You can verify it on NMLS Consumer Access under NMLS #2002997.

Source: NMLS Consumer Access, last verified October 23, 2026.

Can I do my mortgage in German?

Ja. Fabion speaks German and can run the whole process in German, from the first call to the closing table. Zur deutschen Seite.

Does it cost anything to talk to you or use the calculator?

No. The call, the calculator and the Homebuying Snapshot are free, and none of them touch your credit.

Answers last reviewed October 23, 2026. General information, not a commitment to lend. Programs and guidelines can change.

Take the next step

The door’s open.

First home, bigger home, rental or refinance: in about fifteen minutes you’ll know your options, your numbers and your next step. Whichever way it goes, you’ll know.

An open oak front door with pink peonies and house keys on the entry table, desert garden and mountains outside
CallTextApply now